By Michelle Maloney, Broker/Owner, Maloney Real Estate · SD License #14315
What does an FHA 203(k) loan do for an older Yankton home?
It puts the repairs into the mortgage. A 203(k) is FHA’s rehabilitation mortgage. HUD’s program page says the Limited version lets buyers and owners finance up to $75,000 into their mortgage to repair, improve or upgrade the home, and HUD’s July 2024 notice puts the Limited version’s maximum total rehabilitation cost at $75,000 as well.
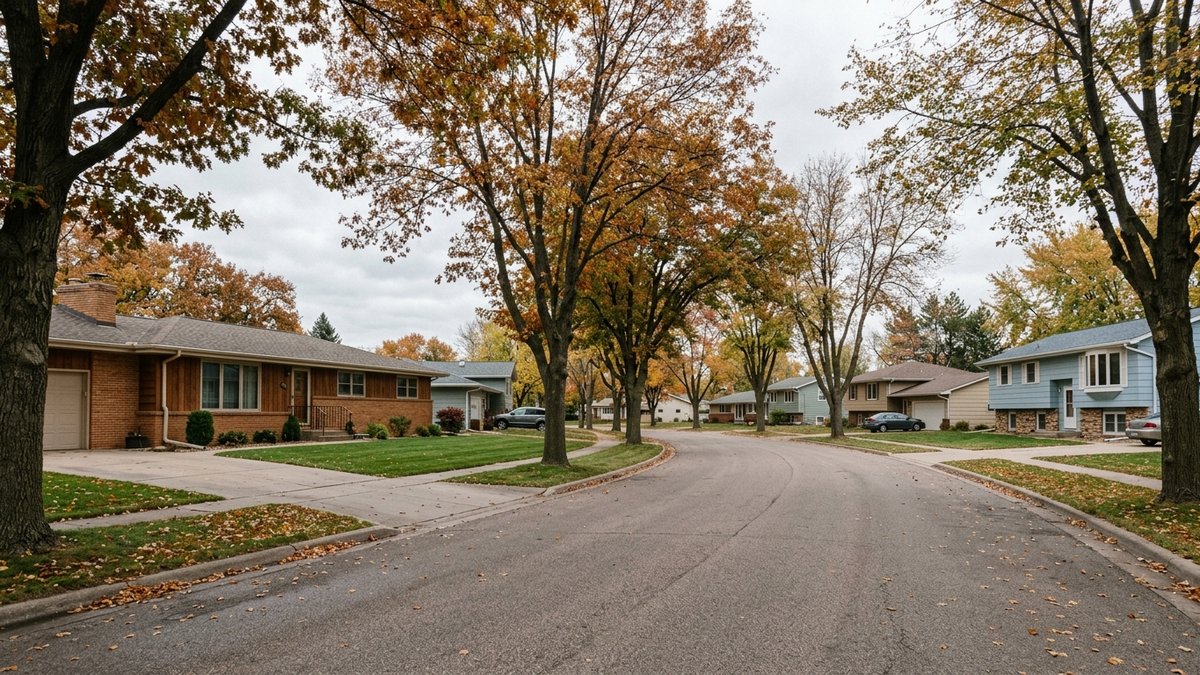
If you’re looking at older houses in Yankton, that changes the question you ask on a showing. You stop asking only whether you like the house as it is. You start asking what it needs, what that work costs and whether the loan can carry both.
Before you go further, write the repair list down in plain words: what’s broken, what’s dated and what you’d change in the first year. That list is what you’ll bring to the lender, and it decides which version of the loan you’re talking about. If you already have an inspection report, start with what the inspector flagged.
Then compare houses the same way. If you’re weighing an older house that needs work against one that’s move-in ready, put both on one page: the price, the repair estimate for the older house and the monthly payment your lender quotes for each. Seeing the totals side by side keeps you from falling for the lower price alone, or from passing on a good house because the list looked long.
You work through an FHA-approved lender. HUD’s program page lists talking to an FHA-approved lender and choosing the 203(k) program as an early step, and HUD’s mortgagee letter sets the program’s rules for FHA-approved lenders. Ask early whether the lender you’re working with handles 203(k) loans. Our guide to mortgage options for Yankton buyers covers how FHA compares with the other loan types.
Which 203(k) version fits your repair list?
The size of the job decides it. There are two versions, and the line between them is about scope.
The Limited 203(k) is for smaller work. HUD’s mortgagee letter says it may only be used for minor remodeling and nonstructural repairs, with total rehabilitation costs up to $75,000, and HUD’s program page says the same. The rehabilitation period is up to nine months, and the work can’t keep you out of the house for more than 30 days. Both the mortgagee letter and HUD’s July 2024 notice set those limits.
The Standard 203(k) is for bigger projects. HUD’s program page describes it as the version for major rehabilitation and repair, and the mortgagee letter says the Limited version can’t be used for major rehabilitation or major remodeling. Both the mortgagee letter and the notice give the Standard version a 12-month rehabilitation period. Both the mortgagee letter and the notice also list financeable mortgage payment reserves among the Standard version’s terms, so ask the lender how that would work if the job keeps you out of the house.
Here’s how to sort your list:
| Your repair list | Likely version | Why |
|---|---|---|
| Minor remodeling and nonstructural repairs, total cost up to $75,000 | Limited | That is the scope HUD sets for the Limited version |
| Major rehabilitation or major remodeling | Standard | The Limited version can’t be used for it |
| Work that would keep you out of the house more than 30 days | Standard | The Limited version caps time out of the home at 30 days |
If you’re not sure where a repair falls, say so to the lender early and ask which version it expects to use. Bring the inspection report and any contractor estimates you have, so the answer is based on the actual list.
What does the 203(k) consultant do?
The consultant turns your repair list into a plan the lender can fund. HUD’s program page and its mortgagee letter both say the consultant inspects the home and prepares a work write-up and cost estimate.
Read the write-up line by line when you get it. Check that every item you care about is on it, that nothing you didn’t ask for crept in, and that the totals match the bids you’ve seen. If something is missing, raise it before the loan moves forward, while it’s still easy to change.
Whether you need one depends on the version. The mortgagee letter says a Standard 203(k) requires a consultant, and a Limited 203(k) doesn’t require one but may use one. HUD’s program page also lists the consultant step as optional for the Limited version. Under the 2024 changes, the consultant fee can be financed in a Limited 203(k), according to both the mortgagee letter and HUD’s notice.
For an older Yankton house, bring your inspection report to the consultant’s visit and go through each item the inspector flagged. Ask how the write-up and the budget handle anything the contractor finds once the walls or floors are open. Our post on what to do when an inspection turns up big issues covers repair requests, credits and other ways buyers handle a long report, and the consultant’s write-up is where the repairs you keep turn into line items and dollars.
When did the 203(k) rules change, and do they apply to you?
They changed in 2024. HUD published Mortgagee Letter 2024-13 on July 9, 2024, and both the letter and HUD’s notice say the changes apply to FHA case numbers assigned on or after November 4, 2024. HUD can update 203(k) guidance again, so ask your lender which rules apply to your loan.
The main changes, as both documents list them:
- the Limited version’s total rehabilitation cost can now reach $75,000
- HUD added an annual review of that Limited cap
- the rehabilitation period is 12 months for the Standard version and nine months for the Limited version
- the Limited version allows up to 30 days when you can’t live in the home during the work
- the consultant fee can be financed in a Limited 203(k)
Because HUD now reviews the Limited cap each year, check the current number with your lender instead of relying on any article, including this one. Ask about timing too. If your purchase straddles a change, the lender can tell you which rules your case number falls under and whether anything in your plan needs to change.
How do you use a 203(k) when you make an offer in Yankton?
Plan the financing before you write. Line these steps up in this order.
- Talk to an FHA-approved lender that does 203(k) loans. Ask which version they expect for the home you’re considering, the current Limited cap and how long their 203(k) process usually takes.
- Get the inspection and a repair scope. You’ll need a list the consultant or contractor can price. Our guide to older home costs in central Yankton walks through the ownership costs to weigh alongside the repairs.
- Ask the lender what it needs from contractors and when, so the bids are in hand before your financing deadline. If a consultant or contractors need to see the house, ask the seller early for access.
- Ask about permits. Ask your contractor which City of Yankton or Yankton County permits the job needs, since that affects the timeline and the budget.
- Build the timeline into your offer. Talk with your agent about financing and closing dates that leave room for the write-up, the bids and underwriting, and be ready to explain that timeline to the seller.
- Check the payment, not just the price. Ask your lender to show the monthly payment with the repair costs included, and decide whether that number works for you before you sign. If it doesn’t, ask the lender and the consultant which repairs the loan requires and whether the scope can change.
If you’re still deciding whether an older home is the right fit, our buyer guide walks through the rest of the purchase, from the first showing to closing day.
Frequently Asked Questions
Is a 203(k) only for people buying a home?
No. HUD's program page describes both versions as available to homebuyers and homeowners, and HUD's July 2024 notice names homebuyers and homeowners among the people the changes were meant to help. If you already own an older Yankton home, ask an FHA-approved lender whether a 203(k) fits your situation.
Why did HUD change the 203(k) in 2024?
Because fewer people were using it. HUD's mortgagee letter says use of the program had declined in recent years, and its July 2024 notice says home buyers took out fewer 203(k) renovation mortgages despite a growing need. Both say FHA asked for public input in February 2023 about the barriers holding the program back before it made the changes.
Can a 203(k) be used to refinance a home I already own?
Yes. HUD's mortgagee letter describes the program as insuring mortgages used to purchase a home or refinance an existing mortgage that include funds for repair or rehabilitation, and HUD's program page says homeowners can finance repairs into their mortgage with the Limited version. An FHA-approved lender can tell you whether a refinance fits your home and your numbers.
Who picks the 203(k) consultant?
The lender, from FHA's list. HUD's program page says the lender selects a HUD-approved consultant from the roster, and HUD's mortgagee letter says the lender must select an FHA-approved consultant who is active on FHA's 203(k) Consultant Roster. FHA is the one that approves consultants onto that roster, according to the mortgagee letter. You can ask the lender for the consultant's name before closing.
Buyer Guides
Buy a Home in Yankton
The buyer service page for search help, offer strategy, and local guidance.
Open guideBuyer Guides
Yankton Buyer Guide
Step-by-step education for financing, inspections, offers, and closing.
Open guideBuyer Guides
Homes for Sale
Current inventory plus local search context by property type and area.
Open guide
About the Author
Michelle Maloney is the Broker/Owner of Maloney Real Estate in Yankton, South Dakota. She helps buyers and sellers understand the local market, compare their options, and make confident real estate decisions across Yankton and southeast South Dakota.
Sources
U.S. Department of Housing and Urban Development, Mortgagee Letter 2024-13, Revisions to the 203(k) Rehabilitation Mortgage Insurance Program (July 9, 2024), U.S. Department of Housing and Urban Development, FHA INFO 2024-44, Updates to the 203(k) Rehabilitation Mortgage Program (July 9, 2024), U.S. Department of Housing and Urban Development, 203(k) Rehabilitation Mortgage Insurance Program Types.
Questions About the Yankton Market?
Ask Michelle's team about pricing, neighborhoods, timing, or your next move. No pitch, no pressure.